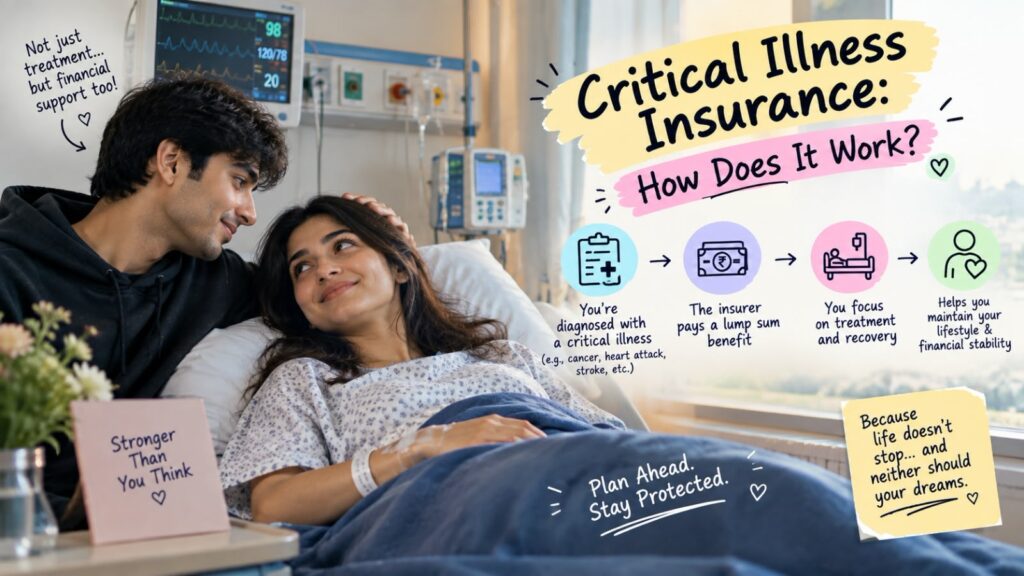
Imagine getting a serious health diagnosis and suddenly having to think about hospital visits, treatment, medicines, and months of recovery—while your regular household expenses continue as usual. This is where Critical Illness Insurance can provide financial support. Unlike regular health insurance, which generally covers eligible medical expenses, a critical illness policy typically pays a lump-sum amount when the insured is diagnosed with a covered critical illness, subject to the policy terms and conditions.
What Is Critical Illness Insurance?
Critical Illness Insurance is a type of health insurance designed to provide financial assistance after the diagnosis of specific serious illnesses listed in the policy.
Depending on the insurer and plan, covered conditions may include illnesses such as:
- Cancer of specified severity
- Heart attack
- Stroke
- Kidney failure
- Major organ transplant
- Coronary artery bypass surgery
- Paralysis
- Multiple sclerosis
- Major burns
The exact list varies from one policy to another. Therefore, it is important to read the policy wording rather than assuming that every serious disease will automatically be covered.
The key difference is how the benefit is paid. Once a covered critical illness is diagnosed and the claim meets the policy conditions, the insurer generally pays the specified sum insured as a lump sum.
This money can then be used according to your needs.
How Does Critical Illness Insurance Work?
Understanding how Critical Illness Insurance works is easier when you look at it as a financial safety net rather than simply another medical policy.
Here is the basic process:
1. You Choose a Sum Insured
You select the amount of coverage based on your income, financial responsibilities, existing health insurance and lifestyle.
For example, suppose you purchase a critical illness policy with a ₹10 lakh sum insured.
2. You Pay the Premium
You pay a premium to keep the policy active. The premium can vary depending on factors such as age, coverage amount, policy terms, medical history and the insurer’s underwriting requirements.
3. A Covered Illness Is Diagnosed
If you are diagnosed with an illness specifically covered under the policy, you can initiate the claim process.
The diagnosis usually needs to satisfy the definition and medical criteria mentioned in the policy document.
4. The Insurer Evaluates the Claim
The insurer reviews the submitted medical documents and checks whether the diagnosis meets the policy’s conditions.
5. Lump-Sum Benefit Is Paid
If the claim is approved, the insured receives the applicable lump-sum benefit according to the policy terms.
Unlike a reimbursement-based hospitalisation claim, this amount is generally not restricted to the actual hospital bill.
What Can You Use Critical Illness Insurance Money For?
One of the biggest advantages of a lump-sum benefit is flexibility.
A serious illness can affect much more than your hospital expenses. You may need money for:
- Treatment and medicines
- Follow-up consultations
- Diagnostic tests
- Household expenses
- EMIs and loan repayments
- Children’s education
- Travel for specialised treatment
- Home modifications or support services
- Loss of income during recovery
For example, if someone needs to take several months away from work, their biggest financial problem may not be the hospital bill—it may be the income they are unable to earn during recovery.
A lump-sum payout can help provide financial breathing room during that period.
Critical Illness Insurance vs Regular Health Insurance
These two types of insurance are often confused, but they serve different purposes.
| Feature | Critical Illness Insurance | Regular Health Insurance |
|---|---|---|
| Benefit type | Usually lump-sum payout | Usually covers eligible medical expenses |
| Trigger | Diagnosis of a specified covered illness | Hospitalisation/treatment as per policy |
| Use of payout | Generally flexible | Primarily linked to covered healthcare expenses |
| Coverage | Specific listed critical illnesses | Broader range of eligible medical treatments |
| Purpose | Financial support after serious illness | Protection against healthcare costs |
For many people, these policies can serve complementary roles rather than being alternatives to one another.
Your regular health insurance may help manage eligible hospitalisation costs, while a critical illness policy can provide additional financial support after a covered diagnosis.
Which Illnesses Are Covered Under Critical Illness Insurance?
Coverage depends entirely on the policy. Some plans may cover a relatively small number of conditions, while others may offer a broader list.
Commonly covered conditions can include:
Cancer
Coverage may apply to cancer meeting the specific definition and severity criteria stated in the policy.
Heart Attack
The policy may specify medical conditions that must be met for a heart attack claim to qualify.
Stroke
Some policies cover stroke subject to defined neurological impairment and other conditions.
Kidney Failure
Permanent kidney failure requiring regular dialysis may be covered under certain plans.
Major Organ Transplant
Some policies provide coverage for specified major organ or bone marrow transplants.
Important: Never select a policy simply because it lists a particular disease. Always check the detailed definition, exclusions, survival period and other claim conditions.
What Is Not Covered Under Critical Illness Insurance?
Every policy comes with exclusions and conditions. These may vary between insurers and products.
Some common exclusions or restrictions can involve:
- Illnesses not included in the policy’s covered list
- Pre-existing conditions, depending on policy terms
- Diagnosis during an applicable waiting period
- Conditions that do not meet the policy’s medical definition
- Self-inflicted injuries or other specified exclusions
- Non-disclosure or incorrect information in the proposal
The exact exclusions should always be checked in the policy wording.
Waiting Period and Survival Period: What Do They Mean?
These terms are particularly important when buying a critical illness policy.
Waiting Period
A waiting period is a specified period during which certain claims may not be payable.
For example, a policy may have an initial waiting period after its commencement. The exact duration and applicability depend on the policy.
Survival Period
Some critical illness policies include a survival period after diagnosis.
For example, if the policy specifies a particular survival period, the insured may need to survive that period after diagnosis for the benefit to become payable.
This is why reading the policy terms is essential before purchasing coverage.
Who Should Consider Critical Illness Insurance?
There is no one-size-fits-all answer, but it may be worth considering if you have significant financial responsibilities.
It can be particularly relevant for people who:
- Have dependent family members
- Are the primary income earner
- Have substantial EMIs or loans
- Have limited emergency savings
- Want additional financial protection against serious illnesses
- Would face financial pressure during a long recovery period
Young professionals should not automatically assume that serious illnesses are only a concern later in life. The financial impact of a major illness can be significant at any age.
How Much Critical Illness Insurance Do You Need?
The right amount depends on your individual financial situation.
Instead of selecting a number randomly, consider:
Annual income + existing financial commitments + potential treatment-related costs + income loss during recovery − available financial resources
For example, someone with a high income, large EMI commitments and dependents may need a different level of protection than someone with fewer financial responsibilities.
It is also worth reviewing your coverage as your income and responsibilities change.
How to Choose Critical Illness Insurance?
Before purchasing a policy, compare more than just the premium.
Look at:
Number of Covered Illnesses
A larger list does not automatically mean better coverage. Check exactly how each illness is defined.
Sum Insured
Choose an amount that could meaningfully support your finances after a serious diagnosis.
Waiting and Survival Periods
Understand when the coverage starts and what conditions apply before a payout becomes payable.
Exclusions
Read the exclusions carefully to understand what the policy does not cover.
Claim Conditions
Check the documents and medical requirements needed to establish a covered diagnosis.
Policy Renewability
Understand the renewal terms and whether the policy can continue as you get older.
Why Critical Illness Insurance Can Be a Financial Planning Tool
A serious illness can create a double financial challenge: higher expenses and potentially lower income.
That is why Critical Illness Insurance can play a role beyond traditional medical expense protection. The lump-sum benefit can provide greater flexibility during a difficult period, helping you manage financial commitments while focusing on recovery.
However, it should generally be viewed as an additional layer of protection rather than a replacement for comprehensive health insurance.
Final Thoughts
Health emergencies can affect your finances in ways that go beyond hospital bills. A serious diagnosis may mean treatment costs, time away from work, ongoing expenses and changes to your family’s financial plans.
Critical Illness Insurance is designed to provide a lump-sum benefit when a covered critical illness is diagnosed, subject to the policy’s definitions, exclusions and claim conditions.
Before buying a policy, compare the covered illnesses, sum insured, waiting period, survival period, exclusions and claim requirements. Most importantly, choose coverage that fits your financial responsibilities rather than simply choosing the cheapest premium.
A well-planned insurance portfolio can help you prepare financially for uncertainties—so that when life gets unpredictable, your finances don’t have to be.