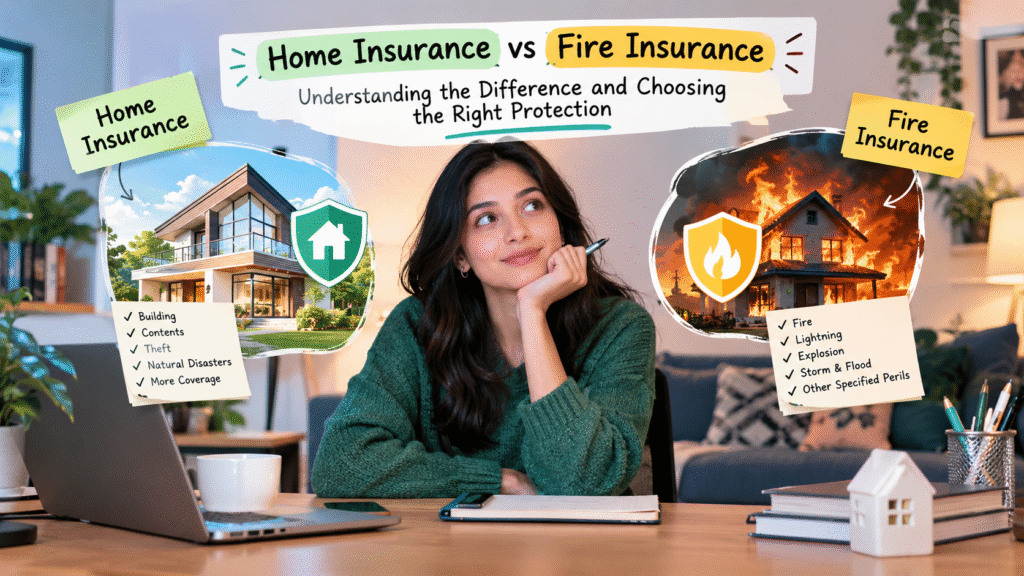
Buying a home is one of the biggest financial milestones in life. But owning a home also means taking responsibility for protecting the building, belongings, and everything you have worked hard to build. This is where understanding Home Insurance vs Fire Insurance becomes important. While both can provide protection against property-related risks, they are not necessarily the same in terms of scope, coverage, and purpose. Knowing the difference can help homeowners make a more informed decision about the type of protection they may need.
What Is Home Insurance?
Home insurance is designed to provide financial protection for your home and, depending on the policy, its contents against specified risks. A home insurance policy may cover the physical structure of your house, household belongings, or both.
For example, imagine a situation where a major storm damages your roof, water enters the house, and some furniture gets damaged. Depending on the policy terms, applicable exclusions, and selected coverage, a home insurance policy may provide protection against some of these losses.
The exact coverage varies from one policy to another, so it is important to read the policy wording instead of assuming that every type of damage is automatically covered.
What Can Home Insurance Cover?
Depending on the policy, home insurance may provide coverage for:
- The building or structure of the house
- Household contents and personal belongings
- Furniture and appliances
- Electrical equipment
- Certain natural or accidental perils
- Fire and related risks
- Theft or burglary, where specifically covered
- Additional living expenses or loss of rent, where included
- Other optional protections or add-ons
The important point is that home insurance is generally broader in concept than protection against fire alone. However, the actual scope depends entirely on the policy selected.
What Is Fire Insurance?
Fire insurance primarily focuses on protecting insured property against fire and other specified perils mentioned in the policy.
In India, Standard Fire and Special Perils (SFSP) policies have historically covered specified risks such as fire, lightning, explosion or implosion, storm, cyclone, flood and inundation, impact damage, and certain other perils, subject to the policy terms and exclusions.
This means the term “fire insurance” can sometimes be misleading. A policy described around fire protection may cover more than just damage caused by flames.
For example, if a fire breaks out due to an electrical short circuit and damages insured property, the policy may respond if the event falls within the policy’s covered perils and conditions.
Is Fire Insurance Only for Fire Damage?
Not necessarily.
A Standard Fire and Special Perils policy can include several specified perils beyond fire. IRDAI-hosted policy wording lists risks including lightning, explosion/implosion, storm, cyclone, flood and inundation, impact damage, bursting or overflowing water tanks and pipes, and certain other events, subject to exclusions and conditions.
Therefore, homeowners should look at the actual list of insured perils, rather than judging a policy only by its name.
Home Insurance vs Fire Insurance: Key Differences
The biggest difference between the two is the scope and purpose of protection.
Home insurance is generally structured around protecting a residential property and may combine building and contents protection with additional covers depending on the product.
Fire insurance, on the other hand, is primarily structured around property damage caused by fire and other specified perils.
Here is a simplified comparison:
| Feature | Home Insurance | Fire Insurance |
|---|---|---|
| Primary purpose | Protection of home and/or contents | Protection against fire and specified perils |
| Building coverage | May be available | Can be covered when included in the policy |
| Contents coverage | May be available | Depends on the policy and insured property |
| Fire damage | Usually covered if included | Core area of protection |
| Natural perils | Depends on policy | May include specified perils such as storm/flood |
| Theft/burglary | May be available depending on policy | Not automatically included |
| Add-ons | Product-dependent | Product-dependent |
| Coverage scope | Can be broader | Focuses on specified property perils |
The table is only a general guide. Actual coverage, exclusions, deductibles, limits, and claim conditions vary by policy.
Home Insurance vs Fire Insurance: Which Risks Are Covered?
When comparing Home Insurance vs Fire Insurance, don’t focus only on the premium. Look carefully at the risks covered and the assets you want to protect.
Fire and Explosion
Fire is one of the major risks addressed by property insurance. However, policies may contain specific exclusions relating to the cause or circumstances of the loss.
For instance, standard fire policy wording can contain exclusions for certain situations involving spontaneous combustion, heating or drying processes, or property destroyed under orders of a public authority.
Natural Disasters
Certain property policies may cover risks such as storms, cyclones, floods and inundation. Whether a particular event is covered depends on the policy wording and applicable exclusions.
Some policies may also offer earthquake-related protection separately or through specific coverage provisions.
Theft and Burglary
Theft and burglary protection should never be assumed simply because you have property insurance. If this protection matters to you, check whether it is specifically included in the policy.
This becomes particularly important when expensive electronics, jewellery, appliances, furniture, or other valuable belongings are kept at home.
Why the Sum Insured Matters
Choosing the right coverage amount is just as important as choosing the type of policy.
Suppose your house is worth considerably more to rebuild than the amount insured under your policy. In the event of a covered loss, inadequate insurance can leave you financially exposed.
For building insurance, homeowners should consider the cost of reconstruction rather than simply looking at the property’s market or resale value. The land value and construction cost are different financial considerations.
For household contents, consider the replacement cost of the belongings you actually want to insure.
Don’t Choose Coverage Only by Premium
A cheaper policy isn’t necessarily suitable if it leaves important risks or belongings outside the coverage you need.
Instead of asking only, “How much is the premium?”, ask:
- What exactly is insured?
- What risks are covered?
- What are the exclusions?
- What is the sum insured?
- Are there deductibles?
- Are valuable items subject to specific limits?
- Are add-ons available?
- What documents are required during a claim?
These questions can make the comparison much more meaningful.
Common Mistakes Homeowners Should Avoid
Property insurance can become confusing when policy terms are not read carefully. Some common mistakes include:
Assuming Every Home-Related Risk Is Covered
Having home insurance does not mean every possible incident is automatically covered. Insurance works according to the terms, conditions, exclusions, limits, and definitions stated in the policy.
Choosing an Unreasonably Low Sum Insured
Underinsuring a property can create a significant financial gap after a major loss.
Ignoring Policy Exclusions
Exclusions are just as important as the list of covered events. Read them carefully before purchasing or renewing the policy.
Not Updating the Policy
If you renovate your house, purchase expensive equipment, or make significant changes to the property, review whether your existing insurance remains appropriate.
Not Keeping Important Documents
Bills, photographs, valuation documents, ownership records, and policy documents can be useful when establishing ownership or supporting a claim, depending on the insurer’s requirements.
Home Insurance vs Fire Insurance: What Should You Consider?
There isn’t one universal answer for every homeowner because the appropriate coverage depends on the property, belongings, risk exposure, budget, and policy terms.
If your primary concern is protecting the structure and contents of your home against a broader range of specified risks, you may want to explore a home insurance product that provides the relevant combination of covers.
If your requirement is specifically focused on property damage arising from fire and other defined perils, a fire and special perils policy may be relevant.
The key is to compare coverage rather than just product names.
How to Choose the Right Property Protection
Before purchasing a policy, make a simple list of what you want to protect:
- Building: Estimate the cost of rebuilding the structure.
- Contents: Identify furniture, appliances, electronics and other important belongings.
- Major risks: Consider fire, natural disasters, theft and other risks relevant to your location.
- Policy limits: Check individual item limits and overall sum insured.
- Exclusions: Understand what the insurer will not cover.
- Deductibles: Know how much you may have to bear yourself during a claim.
- Add-ons: Consider additional covers only when they address a genuine need.
You can then compare policies based on their actual benefits and conditions.
Final Thoughts
Your home represents much more than bricks, walls, furniture, and appliances. It represents years of savings, effort, and personal memories. That is why understanding the difference between different forms of property protection matters.
When evaluating Home Insurance vs Fire Insurance, focus on what you own, what risks you want to protect against, and what each policy actually covers. Don’t rely solely on the policy name or premium. Read the coverage, exclusions, limits, deductibles, and claim conditions carefully.
At Growease, we believe financial protection should be easier to understand. Whether you’re exploring insurance, investments, mutual funds, loans, or corporate fixed deposits, understanding your options can help you make more informed financial decisions.