Medical expenses can show up when you least expect them. Even if you already have health insurance, a major hospitalisation can quickly make you wonder whether your existing coverage is actually enough. This is where understanding Top-up vs Super Top-up health insurance becomes important. Both options can increase your health coverage at a relatively affordable premium, but they work differently. Knowing that difference can help you choose coverage that matches your healthcare needs and budget.
What Is Top-up Health Insurance?
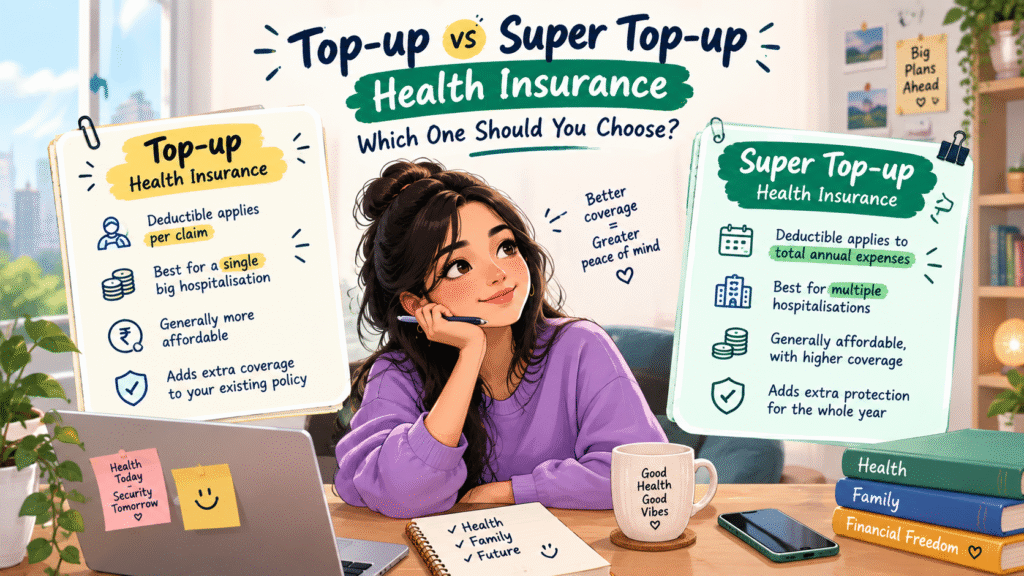
A top-up health insurance plan provides additional coverage once your medical expenses cross a specified deductible. However, there is an important catch: the deductible generally applies to each individual claim.
For example, suppose you have:
- Existing health insurance: ₹5 lakh
- Top-up cover: ₹10 lakh
- Deductible: ₹5 lakh
If you are hospitalised and the eligible bill is ₹8 lakh, the top-up policy can cover the amount above the ₹5 lakh deductible, subject to the policy terms.
But what happens if you have two separate hospitalisation claims of ₹4 lakh each in the same policy year? Since neither individual claim crosses the ₹5 lakh deductible, the top-up may not pay anything.
This claim-wise deductible is the biggest feature you need to understand before buying a top-up plan.
What Is Super Top-up Health Insurance?
A super top-up health insurance plan also provides additional coverage after you cross a predefined deductible. The key difference is that the deductible is generally calculated based on the total eligible medical expenses incurred during the policy year, subject to the policy wording.
For example, imagine:
- Existing health insurance: ₹5 lakh
- Super top-up cover: ₹10 lakh
- Annual deductible: ₹5 lakh
During the year, you have three eligible medical expenses:
- Hospitalisation 1: ₹3 lakh
- Hospitalisation 2: ₹2 lakh
- Hospitalisation 3: ₹4 lakh
Your cumulative eligible expenses reach ₹5 lakh after the first two claims. The super top-up can then respond to eligible expenses beyond the deductible, subject to the sum insured and policy conditions.
This makes super top-ups particularly relevant for people who are concerned about multiple hospitalisations in one policy year.
Top-up vs Super Top-up Health Insurance: Key Difference
When comparing Top-up vs Super Top-up health insurance, the biggest difference is how the deductible is calculated.
| Feature | Top-up Health Insurance | Super Top-up Health Insurance |
|---|---|---|
| Deductible | Usually applies per claim | Usually applies to cumulative eligible expenses during the policy year |
| Multiple claims | Each claim generally needs to cross deductible | Multiple claims can collectively cross deductible |
| Premium | Generally affordable | Generally affordable, though pricing varies |
| Useful for | A large single hospitalisation | Multiple hospitalisations or medical expenses |
| Existing health cover | Can supplement base policy | Can supplement base policy |
| Policy conditions | Vary by insurer | Vary by insurer |
The exact operation, exclusions, waiting periods, eligible expenses and deductible conditions can differ between policies. Always read the policy wording before purchasing.
How Does a Top-up Health Insurance Plan Work?
Let’s make it simple.
Suppose your top-up policy has a ₹5 lakh deductible and ₹10 lakh sum insured.
Scenario 1: One large claim
You receive a hospital bill of ₹9 lakh.
After applying the deductible, the eligible amount above ₹5 lakh may be covered by the top-up, subject to policy terms.
Scenario 2: Two smaller claims
Now imagine you have:
- First claim: ₹3 lakh
- Second claim: ₹4 lakh
Although your total medical expenses are ₹7 lakh, neither individual claim crosses the ₹5 lakh deductible.
Therefore, a standard top-up may not provide the expected additional benefit.
This is why understanding the deductible mechanism matters more than simply looking at the headline coverage amount.
How Does a Super Top-up Health Insurance Plan Work?
A super top-up is designed differently.
Suppose your deductible is ₹5 lakh and your super top-up sum insured is ₹10 lakh.
During the same policy year, you incur:
- First hospitalisation: ₹3 lakh
- Second hospitalisation: ₹4 lakh
Your cumulative eligible expenses become ₹7 lakh.
Once the annual deductible is crossed, the super top-up can cover eligible expenses above the deductible, according to the policy’s terms and limits.
This can make it useful when medical expenses occur through multiple hospitalisations or treatments within the same policy year.
Top-up vs Super Top-up Health Insurance: Which One Is More Suitable?
There isn’t one option that works perfectly for everyone. Your choice should depend on your existing health insurance, financial situation, family structure and expected healthcare requirements.
A Top-up May Suit You If:
A top-up can be considered when your primary concern is protection against a single high-value hospitalisation.
For example, if you already have ₹5 lakh of base health insurance and want additional protection against a major medical bill, a top-up may provide an economical way to increase your potential coverage.
However, check whether the deductible is per claim and understand exactly how claims will be settled.
A Super Top-up May Suit You If:
A super top-up may be more relevant if you want additional protection against multiple medical expenses during a policy year.
For families, older individuals or people who are concerned about repeated hospitalisations, cumulative expenses can become significant.
Again, the policy wording is crucial because not every plan has identical definitions or claim conditions.
Why Should You Consider Additional Health Insurance Coverage?
Healthcare costs don’t always follow a predictable pattern.
One year, you may barely use your health insurance. The next year, an unexpected surgery, accident or prolonged treatment could result in a large bill.
Your existing ₹5 lakh or ₹10 lakh policy may feel sufficient today, but medical costs can rise over time.
A top-up or super top-up can potentially provide an additional layer of financial protection without requiring you to replace your existing health insurance policy.
Think of it like this:
Base policy = first layer of protection
Top-up/Super top-up = additional financial cushion
This layered approach can be particularly useful when you want higher overall coverage while keeping premiums within a manageable range.
Factors to Check Before Buying a Top-up or Super Top-up
Don’t select a plan simply because it offers a large sum insured at a low premium. Check the details carefully.
1. Deductible
Understand whether the deductible applies per claim or cumulatively. This is one of the most important differences between the two products.
2. Sum Insured
Check whether the additional coverage is sufficient for your family and the healthcare costs you want to protect against.
3. Waiting Periods
Look for initial waiting periods, specific disease waiting periods and pre-existing disease conditions.
4. Room Rent and Other Limits
Sub-limits can affect the amount payable during a claim. Review room-rent restrictions, disease-specific limits and other applicable caps.
5. Network Hospitals
Check whether your preferred hospitals are included in the insurer’s cashless network.
6. Exclusions
Every policy has exclusions. Understanding what isn’t covered can prevent unpleasant surprises during a claim.
7. Claim Process
Review the insurer’s claim procedure and documentation requirements. A policy is useful only when you understand how to use it when you need it.
Top-up vs Super Top-up Health Insurance: A Simple Example
Let’s consider a family that already has ₹5 lakh of base health insurance.
They are considering another ₹10 lakh of coverage.
If their concern is mainly one major hospitalisation, a top-up could be considered, depending on the deductible and policy terms.
If their concern is several hospitalisations adding up over the year, a super top-up could potentially provide more relevant protection because the deductible is generally linked to cumulative eligible expenses.
The important point is that ₹10 lakh top-up and ₹10 lakh super top-up do not necessarily work in the same way.
Common Mistakes to Avoid
Many people make the mistake of comparing plans only on premium and sum insured.
Avoid these common mistakes:
- Choosing the lowest premium without checking coverage
- Ignoring the deductible structure
- Assuming every medical expense will count toward the deductible
- Not checking waiting periods
- Ignoring exclusions and sub-limits
- Forgetting to review the policy when family circumstances change
- Assuming a super top-up works exactly like a regular health insurance policy
A few minutes spent understanding the policy can make a significant difference when you actually need to file a claim.
Final Thoughts
The right health insurance strategy isn’t necessarily about buying the biggest policy. It’s about creating coverage that fits your healthcare risks and finances.
When comparing Top-up vs Super Top-up health insurance, focus on the deductible structure, number of expected claims, sum insured, exclusions, waiting periods and your existing base policy. A top-up can be useful for protection against a large individual claim, while a super top-up may be worth considering when cumulative medical expenses across multiple claims are a concern.
Before making a decision, compare policy terms carefully and consider taking professional guidance to understand how the coverage fits with your existing health insurance.