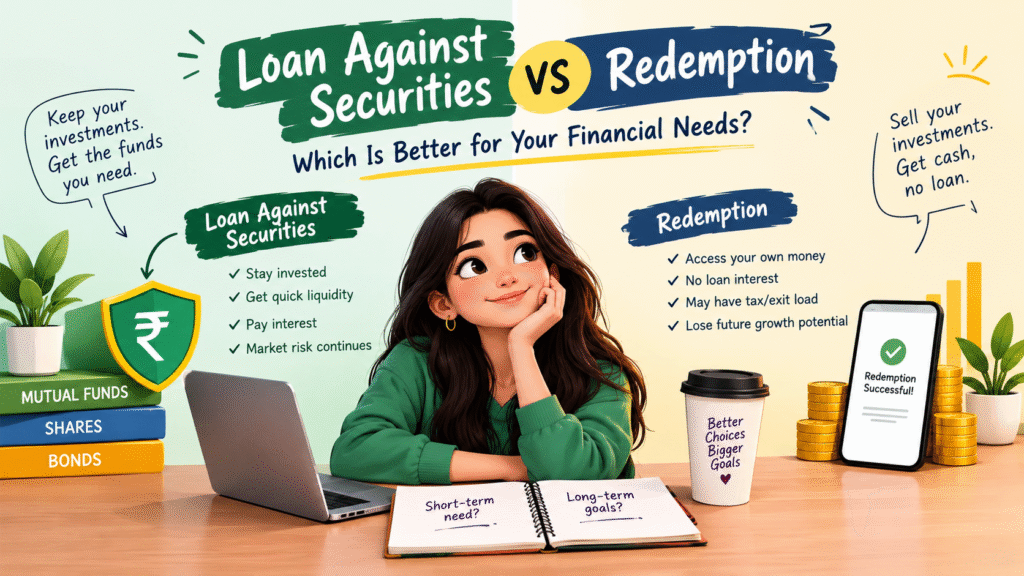
When you need money urgently, selling your investments may seem like the easiest solution. But there is another option: borrowing against them while keeping them invested. Understanding loan against securities vs redemption can help you decide whether it is smarter to access liquidity through a loan or sell your investments. The right choice depends on factors such as your cash requirement, investment goals, market conditions, loan costs, and how long you need the money.
What Is a Loan Against Securities?
A Loan Against Securities (LAS) allows you to borrow money by pledging eligible investments such as mutual funds, shares, bonds, or other approved securities as collateral.
Instead of selling your investments, you temporarily pledge them to the lender. The lender provides a loan based on a percentage of the value of your securities, known as the Loan-to-Value (LTV) ratio.
For example, suppose your eligible investments are worth ₹10 lakh and the lender allows an LTV of 50%. You may be able to borrow around ₹5 lakh against those investments.
Your investments remain yours, but they are pledged until the loan is repaid.
How Does a Loan Against Securities Work?
The process is generally straightforward:
- You hold eligible securities in your investment account.
- You apply for a loan against those securities.
- The lender evaluates the securities and their market value.
- The securities are pledged as collateral.
- You receive the approved loan amount.
- You pay interest according to the loan terms.
- Once the loan is repaid, the pledge can be released.
One important point to remember is that securities are market-linked. If their value falls significantly, the lender may require additional collateral or repayment to maintain the required LTV.
What Does Redemption Mean in Investments?
Redemption means selling your investment and receiving the proceeds in cash.
For example, if you have ₹5 lakh invested in mutual funds and redeem ₹2 lakh, units worth ₹2 lakh are sold and the money is credited to you after applicable processes, charges, taxes, or deductions.
Redemption gives you direct access to your own money without creating a loan obligation.
However, selling an investment also means you may lose the opportunity to participate in its future growth.
When Does Redemption Make Sense?
Redemption may be suitable when:
- You do not want to take on debt.
- You have no regular repayment capacity.
- The investment no longer fits your financial goals.
- You need money for a long-term expense.
- The cost of borrowing is higher than the potential benefit of staying invested.
- You have sufficient investments and can comfortably sell a portion without affecting your goals.
Loan Against Securities vs Redemption: Key Differences
The biggest difference between loan against securities vs redemption is what happens to your investment.
With LAS, you borrow against your investment and generally remain invested. With redemption, you sell the investment to generate cash.
| Factor | Loan Against Securities | Redemption |
|---|---|---|
| Ownership of investment | Generally retained | Investment is sold |
| Interest cost | Yes | No loan interest |
| Repayment | Required | Not applicable |
| Future market participation | Generally continues | Reduced or eliminated for redeemed amount |
| Market risk | Continues | Reduced on redeemed portion |
| Tax impact | Depends on circumstances | Capital gains/tax implications may apply |
| Liquidity | Borrowed funds | Cash from sale |
| Best suited for | Short/medium-term liquidity needs | Situations where selling is financially appropriate |
This makes the decision less about choosing a universally “better” option and more about choosing what fits your financial situation.
Loan Against Securities vs Redemption: Which Costs More?
Cost is one of the most important factors.
A LAS comes with an interest rate and potentially other charges. The longer you keep the loan, the more interest you may pay.
Redemption does not involve loan interest, but selling investments can have other financial consequences. Depending on the investment, you may face capital gains taxation, exit loads, or lose potential future returns.
Consider the Opportunity Cost
Imagine you have ₹10 lakh invested and need ₹3 lakh.
If you redeem ₹3 lakh, that amount is no longer invested. If the remaining investment grows, you participate only with the amount still invested.
With LAS, you may retain the investment while accessing liquidity, but you now have an interest-bearing liability.
Neither option is automatically cheaper. You need to compare the cost of borrowing against the potential benefits and costs of remaining invested.
Loan Against Securities vs Redemption During Market Volatility
Market conditions can influence your decision significantly.
Suppose the market has fallen and your investments are temporarily worth less than their previous value. Redeeming during a downturn could mean selling at an unfavorable point and potentially locking in losses.
A LAS may allow you to access funds without immediately selling the investment.
However, there is an important catch: the pledged securities continue to carry market risk. If their value falls substantially, the lender may reduce the available borrowing limit or ask you to provide additional securities/margin.
So, LAS should not be viewed as a way to eliminate investment risk.
What If the Market Rises?
If your investments appreciate while they are pledged, you continue to remain exposed to that potential upside, subject to the terms of the arrangement.
But remember: investment returns are never guaranteed, while loan interest is a real financial cost.
This distinction is crucial when evaluating your options.
When Should You Choose a Loan Against Securities?
A LAS can potentially make sense when you:
- Need funds for a relatively short period.
- Have a sizeable portfolio of eligible securities.
- Have predictable income to service the interest.
- Do not want to disturb a long-term investment strategy.
- Need liquidity but want to avoid immediately selling investments.
For example, a business owner facing a temporary working-capital requirement may consider LAS instead of liquidating a long-term investment portfolio.
Similarly, an investor facing a short-term financial gap may consider borrowing rather than selling investments intended for a future goal.
When Should You Consider Redemption Instead?
Redemption may be more appropriate when taking on debt would put pressure on your finances.
Consider redemption if:
- Your income is uncertain.
- You cannot comfortably pay loan interest.
- You need money for an extended period.
- The investment has already achieved its intended goal.
- Your investment allocation needs rebalancing.
- Borrowing costs are too high compared with the expected benefit of remaining invested.
For instance, if you need ₹2 lakh but already have excess investments that are not linked to an important financial goal, selling a portion could be simpler than creating a new liability.
Loan Against Securities vs Redemption: Tax and Investment Considerations
Taxes can make the decision more nuanced.
When you redeem or sell certain investments, you may generate a capital gain or loss. The tax treatment depends on the type of security, holding period, applicable tax rules, and other circumstances.
A loan itself is generally not the same as selling an investment because you are borrowing rather than disposing of the asset. However, the exact tax and regulatory implications can depend on the structure and purpose of the transaction.
Before making a large investment decision, it is sensible to evaluate the current tax rules and consult a qualified tax professional where necessary.
Questions to Ask Before Choosing
Before deciding between the two options, ask yourself:
1. How much money do I actually need?
Avoid borrowing or redeeming more than necessary. Calculate the exact requirement first.
2. How long will I need the money?
LAS can be useful for temporary liquidity, but keeping a loan for a long period can increase your interest burden.
3. Can I comfortably service the loan?
A loan should not create unnecessary pressure on your monthly cash flow.
4. Is this investment meant for an important financial goal?
If the investment is earmarked for your child’s education, retirement, or another long-term goal, selling it could disrupt your financial plan.
5. What happens if the market falls?
With pledged securities, a significant market decline can affect your borrowing capacity. Always understand the lender’s margin and collateral requirements.
The Bottom Line
There is no one-size-fits-all answer to loan against securities vs redemption. A loan against securities can provide liquidity while allowing you to remain invested, but it comes with interest costs and market-related collateral risks. Redemption provides cash without creating debt, but it reduces your investment exposure and may have tax or other financial consequences.
The smartest decision is the one that supports both your current cash requirement and long-term financial goals. Before choosing, compare the loan interest, investment horizon, taxation, market conditions, repayment ability, and purpose of the funds.
If you are unsure whether to borrow against your investments or redeem them, a financial professional can help you evaluate the options based on your overall portfolio and financial objectives.