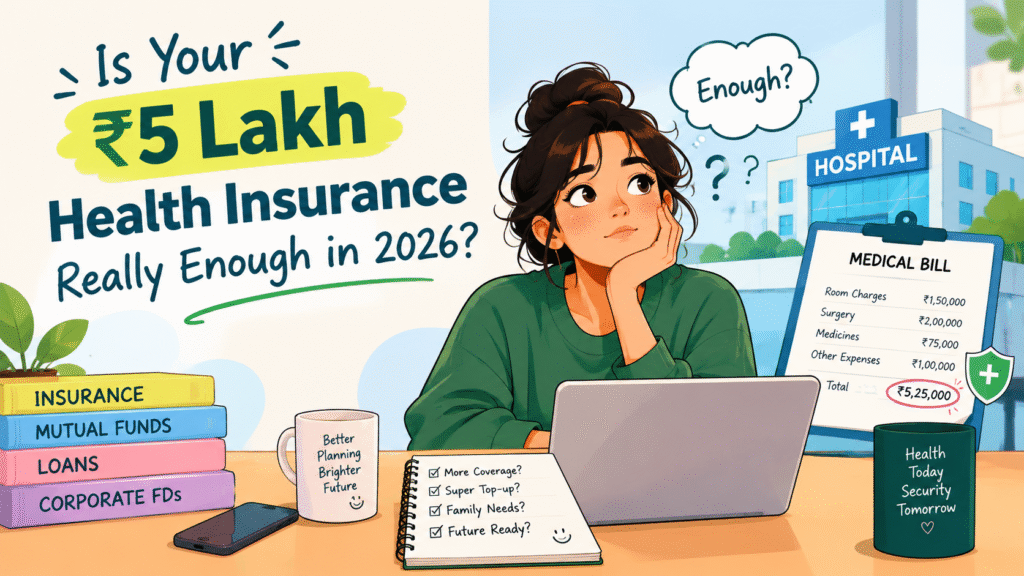
Medical expenses in India have changed dramatically over the years. A treatment that once cost a few thousand rupees can now run into lakhs, especially when hospitalization, surgery, advanced diagnostics or prolonged treatment is involved. This raises an important question for families: Is ₹5 Lakh Health Insurance really enough in 2026? While a ₹5 lakh sum insured may sound substantial, rising healthcare costs and expensive private hospitals can make that coverage feel much smaller when you actually need it.
The right health insurance coverage isn’t about choosing the biggest number. It’s about understanding your family’s healthcare needs, medical inflation, location, age, existing conditions and the kind of hospitals you are likely to use.
Is ₹5 Lakh Health Insurance Enough in 2026?
There is no universal answer. For a young individual with limited medical requirements, ₹5 lakh may provide a reasonable starting point. However, for a family, older parents or someone living in a major city where private healthcare is expensive, the same amount may not provide sufficient financial protection.
Imagine this.
You are admitted to a private hospital for a serious medical procedure. The hospital bill includes room charges, surgeon fees, medicines, diagnostic tests, ICU expenses and other associated costs. If the final bill reaches ₹6–8 lakh, a ₹5 lakh policy may leave you paying the remaining amount from your own pocket, depending on your policy terms and applicable deductions.
That’s where the question of ₹5 Lakh Health Insurance becomes more complicated than simply asking whether ₹5 lakh sounds like a large amount.
Healthcare Costs Are Increasing
Healthcare expenses don’t remain constant. Hospital infrastructure, technology, specialist consultations, medicines and advanced procedures can become increasingly expensive.
Even a routine hospitalization can involve several separate expenses. A health insurance policy that appears sufficient today may provide less protection several years later if medical costs continue increasing.
That’s why reviewing your health insurance periodically is just as important as buying it in the first place.
Why ₹5 Lakh Health Insurance May Fall Short
A ₹5 lakh cover can work for certain situations, but there are several reasons why you shouldn’t automatically assume it will cover every medical emergency.
1. One Major Hospitalization Can Use Most of the Cover
Suppose your policy has a ₹5 lakh sum insured and you undergo treatment costing ₹4 lakh. A significant portion of your annual coverage has already been consumed.
If another hospitalization occurs during the same policy year, your remaining coverage may be considerably lower, depending on the policy’s restoration and refill features.
2. Family Floater Policies Cover Everyone
This is particularly important for families.
If a family has a ₹5 lakh family floater policy, the entire ₹5 lakh is generally shared among the insured members rather than being ₹5 lakh for each person.
For example, if one family member uses ₹3 lakh for hospitalization, only the remaining eligible coverage is available to the others during that policy period, subject to policy terms.
For a growing family, this can make a seemingly adequate amount feel surprisingly small.
3. Room Rent and Policy Conditions Matter
Your sum insured isn’t the only thing that matters.
Some policies may have room-rent restrictions, sub-limits, deductibles, co-payments or exclusions. These conditions can affect how much of the hospital bill the insurer actually pays.
Therefore, comparing policies solely based on the headline sum insured can be misleading.
How Much Health Insurance Should You Consider in 2026?
Instead of choosing an arbitrary number, consider your personal circumstances.
For Young Individuals
A young, healthy individual with no dependents may consider ₹5 lakh as a starting level of coverage. However, adding a higher base cover or a suitable super top-up can provide greater protection against expensive hospitalization.
For Young Families
Families should consider that multiple people may need healthcare during the same year.
A couple with children may find a higher family floater more comfortable than relying only on a ₹5 lakh cover. The appropriate amount will depend on family size, age, location and budget.
For Parents and Older Adults
Healthcare requirements generally become more important with age. Parents may also have greater chances of requiring hospitalization or ongoing treatment.
For this reason, relying solely on a small base cover may not always be ideal. Policy terms, waiting periods, exclusions and pre-existing disease conditions should be carefully evaluated.
What Should You Check Besides the Sum Insured?
The amount of coverage is important, but it isn’t the complete story.
Before purchasing or renewing a health insurance policy, check:
- Room-rent limits
- ICU coverage
- Co-payment requirements
- Waiting periods
- Pre-existing disease clauses
- Network hospitals
- Day-care procedures
- Pre- and post-hospitalization coverage
- Restoration or recharge benefits
- No-claim benefits
- Exclusions and permanent exclusions
- Claim settlement process
- Sub-limits on specific treatments
A ₹10 lakh policy with restrictive conditions may sometimes be less useful than a ₹5 lakh policy with broader and more suitable coverage.
The objective should be to find a policy that provides meaningful protection when you actually need it.
Can a Super Top-Up Solve the Coverage Problem?
One practical strategy is to combine a base health insurance policy with a super top-up.
A super top-up policy can provide additional financial protection after eligible medical expenses cross a specified deductible, according to its terms.
For example, instead of immediately buying an extremely expensive base policy, some individuals may consider maintaining an appropriate base cover and adding a super top-up for larger medical emergencies.
This can potentially provide higher overall protection while keeping the premium more manageable.
However, the deductible, coverage conditions, exclusions and claim structure should always be understood before purchasing.
Is ₹5 Lakh Health Insurance Enough for Your Family?
The answer depends on your family’s financial and healthcare profile.
Consider these questions:
How many people are covered?
A ₹5 lakh individual cover is very different from a ₹5 lakh family floater.
Where do you live?
Treatment costs can vary significantly between cities and healthcare providers.
How old are the insured members?
Healthcare requirements can change considerably with age.
Do you have existing medical conditions?
Pre-existing conditions can influence policy eligibility, waiting periods and coverage.
Do you prefer private hospitals?
If you typically use premium private hospitals, your potential hospitalization expenses may be considerably higher.
Can you afford a large unexpected medical bill?
If paying several lakhs from your savings would significantly affect your finances, higher insurance protection deserves serious consideration.
How to Review Your Health Insurance in 2026
Your health insurance shouldn’t be something you buy once and forget.
At least once a year, review your coverage and ask whether your existing policy still matches your current situation.
Check whether your income has increased, your family has grown, your parents have become older, your medical requirements have changed or your financial responsibilities have increased.
If your existing coverage feels inadequate, you can explore options such as increasing your base sum insured, adding a super top-up or restructuring your overall health insurance portfolio.
The important thing is not to wait until a medical emergency exposes a coverage gap.
Final Thoughts: Don’t Judge Your Health Cover by the Number Alone
A ₹5 lakh policy isn’t automatically bad, and a ₹20 lakh policy isn’t automatically perfect.
What matters is whether the policy is suitable for your circumstances.
In 2026, increasing healthcare costs make it more important than ever to look beyond the headline sum insured. Understand the policy wording, check exclusions and sub-limits, consider your family’s needs and review your coverage regularly.
If your current ₹5 Lakh Health Insurance was purchased several years ago, this could be a good time to reassess whether it still provides the level of financial protection you would expect during a major medical emergency.
Need help reviewing your insurance coverage?
Growease can help you understand your insurance requirements and explore suitable insurance solutions based on your needs, budget and financial goals.