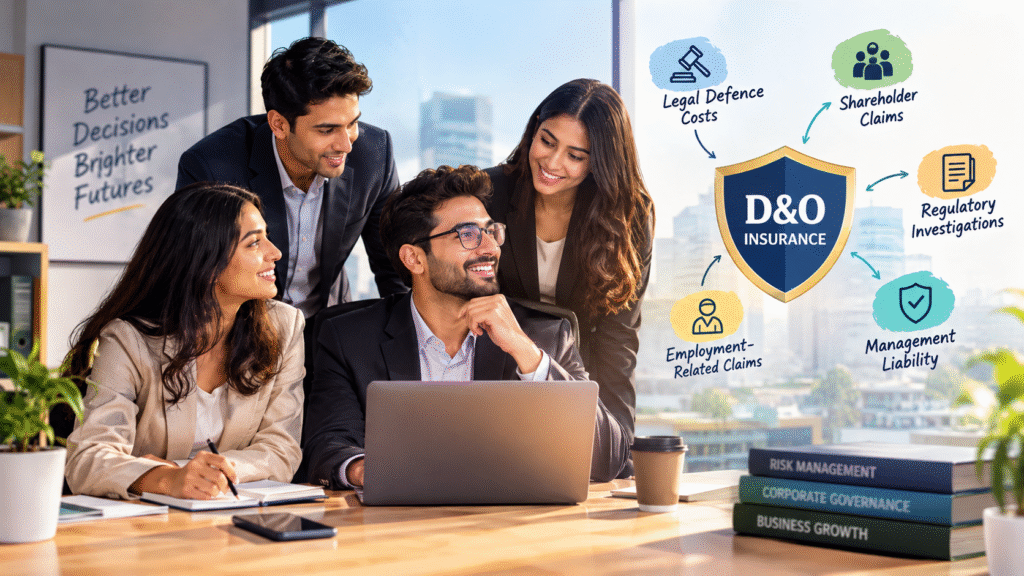
Running a company comes with big decisions—and big responsibilities. Directors and senior officers are expected to make strategic choices every day, but even a well-informed decision can sometimes lead to a legal complaint. Directors and Officers Insurance helps protect company directors and officers from certain personal financial losses arising from claims related to their managerial decisions and actions.
For growing businesses, this type of insurance can be an important part of a broader corporate risk-management strategy. It can provide financial support for eligible legal defence costs, settlements and other covered expenses when directors or officers face claims connected with their professional responsibilities.
What Is Directors and Officers Insurance?
Directors and Officers Insurance, commonly known as D&O Insurance, is designed to protect directors, officers and other eligible senior executives against certain claims arising from their decisions or actions while managing a company.
Imagine a director approves a major business expansion after reviewing available information. Later, shareholders believe the decision caused financial losses and allege that the director failed in their responsibilities. The director may have to respond to the allegation, hire lawyers and potentially face substantial legal expenses.
This is where D&O coverage can become valuable. Depending on the policy terms, it may help cover defence costs and other covered liabilities.
It is important to remember that D&O insurance does not mean every mistake or allegation is automatically covered. Coverage depends on the wording, exclusions, limits, conditions and circumstances of the individual policy.
Why Is Directors and Officers Insurance Important?
Corporate decision-making has become increasingly complex. Directors and officers may face scrutiny from shareholders, employees, regulators, customers, creditors and other stakeholders.
Even when a director has acted honestly and responsibly, defending an allegation can be expensive and time-consuming.
Directors and Officers Insurance can help reduce the financial burden associated with covered claims and give senior management greater confidence when making important business decisions.
For companies, the benefits can include:
- Protection for eligible directors and officers
- Support for covered legal defence expenses
- Financial protection against certain management-related claims
- Better risk-management planning
- Greater confidence for senior executives
- Potentially improved ability to attract experienced leadership
What Does Directors and Officers Insurance Protect Against?
The exact protection varies between policies, but D&O insurance can generally respond to certain claims alleging wrongful acts, errors, omissions, breaches of duty or other management-related failures.
1. Allegations of Wrongful Acts
Directors and officers may be accused of making decisions that negatively affected shareholders, employees or other stakeholders.
A wrongful act could involve an alleged error, omission, misstatement, neglect or breach of duty made in a managerial capacity.
A D&O policy may provide protection for covered claims arising from such allegations.
2. Legal Defence Costs
One of the biggest concerns when a director faces a legal claim is the cost of defending it.
Lawyers, court proceedings, documentation and professional advice can become expensive, even when the director ultimately succeeds.
Depending on the policy, D&O insurance may cover eligible defence expenses associated with covered claims, subject to applicable limits and conditions.
3. Shareholder Claims
Shareholders may bring claims against directors when they believe management decisions have harmed the company or reduced shareholder value.
For example, shareholders might allege that directors failed to properly assess a major transaction or made decisions without adequate consideration of relevant information.
D&O insurance may provide protection for eligible claims of this nature, depending on the policy.
4. Employment-Related Management Claims
Certain policies may provide coverage for claims involving employment practices and management decisions, although this can vary significantly.
Allegations may relate to issues such as wrongful termination, discrimination, harassment or other employment-related decisions.
Businesses should carefully check whether employment practices liability is included, separately endorsed or excluded.
5. Regulatory and Investigative Matters
Directors and officers can sometimes face investigations or regulatory proceedings connected with their managerial responsibilities.
Depending on the policy wording, certain investigation-related expenses may be covered.
However, not every regulatory action or penalty is necessarily insurable, so businesses should understand the exact scope of their policy before relying on this protection.
Who Can Be Covered Under Directors and Officers Insurance?
D&O policies are generally designed for individuals who hold managerial or decision-making responsibilities within an organisation.
Depending on the policy structure, insured persons may include:
- Directors
- Executive directors
- Non-executive directors
- Officers
- Senior management personnel
- Board members
- Certain employees acting in managerial capacities
Coverage can differ depending on the organisation, policy and insurer. Companies should therefore identify the individuals and positions that need protection when purchasing the policy.
What Is Usually Not Covered?
Understanding exclusions is just as important as understanding benefits.
Directors and Officers Insurance generally does not provide unlimited protection against every type of corporate dispute. Policies can contain exclusions for matters such as:
- Fraud or deliberately dishonest acts
- Personal profit obtained illegally
- Known claims or circumstances existing before the policy
- Certain contractual disputes
- Bodily injury or property damage, where separately insured
- Certain criminal proceedings or penalties
- Claims involving specific excluded circumstances
The exact exclusions depend on the policy wording. Therefore, businesses should read the terms carefully instead of assuming that every management-related dispute will be covered.
D&O Insurance vs Professional Indemnity Insurance
D&O insurance and professional indemnity insurance may sound similar, but they protect against different types of risks.
D&O insurance primarily focuses on claims against directors and officers arising from their managerial decisions and responsibilities.
Professional indemnity insurance, on the other hand, is generally designed to protect professionals against claims alleging errors, omissions or negligence in the professional services they provide.
For example, a company director facing a shareholder claim over a management decision may need D&O protection, while a professional consultant facing a claim over incorrect professional advice may require professional indemnity insurance.
Businesses may need one or both depending on their activities and risk profile.
How Does Directors and Officers Insurance Work?
The process generally begins when an insured person becomes aware of a claim or circumstance that could lead to a claim.
The insured should notify the insurer according to the policy’s reporting requirements. The insurer then assesses whether the matter falls within the policy’s coverage.
If the claim is covered, the policy may respond to eligible defence costs, settlements or other covered liabilities, subject to the policy limit, deductible and terms.
Because notification requirements can be important, companies should avoid delaying the reporting of a potential claim.
How Much D&O Insurance Does a Company Need?
There is no universal coverage amount that works for every company.
The appropriate limit may depend on factors such as:
- Company size
- Industry and business activities
- Number of directors and officers
- Revenue and financial position
- Ownership structure
- Regulatory environment
- Litigation exposure
- Business expansion plans
- Existing insurance policies
A startup with a small management team may have a different risk profile from a large listed company with numerous shareholders and significant regulatory exposure.
Businesses should assess their potential exposure rather than choosing a limit simply because it is commonly purchased in their industry.
How Should Businesses Choose a D&O Policy?
Before purchasing a policy, businesses should look beyond the premium.
Consider the following:
Coverage scope: Understand which directors, officers and managerial roles are insured.
Policy limits: Check whether the limit is appropriate for the company’s potential exposure.
Deductibles: Understand how much the insured may need to pay before the policy responds.
Exclusions: Carefully review what the insurer does not cover.
Claims process: Check how claims and circumstances must be reported.
Defence costs: Understand whether defence expenses are included within the overall policy limit or treated separately.
Insurer experience: Consider the insurer’s reputation, financial strength and claims-handling capabilities.
Why D&O Insurance Matters for Growing Businesses
As a business grows, decision-making becomes more complicated. New investors, employees, contracts, regulations and expansion plans can increase the responsibilities placed on directors and officers.
A single allegation can potentially create significant financial and reputational pressure.
Having suitable Directors and Officers Insurance can help businesses manage this uncertainty and provide a layer of financial protection for eligible management-related claims.
It should, however, be viewed as one component of a wider corporate risk-management strategy—not a replacement for good governance, compliance and responsible decision-making.
Final Thoughts
Directors and officers carry significant responsibility for the direction and performance of a company. While good governance can reduce risks, it cannot eliminate the possibility of allegations or legal claims.
Directors and Officers Insurance can provide valuable protection against certain claims arising from management decisions, helping eligible directors and officers manage covered legal and financial exposures.
Before selecting a policy, businesses should carefully evaluate their risks, understand exclusions and limits, and compare the coverage offered rather than focusing only on the premium. Professional guidance can also help a company determine whether the policy is appropriate for its particular needs.